Congress Proposes Crypto Tax Overhaul to Raise $500 Million
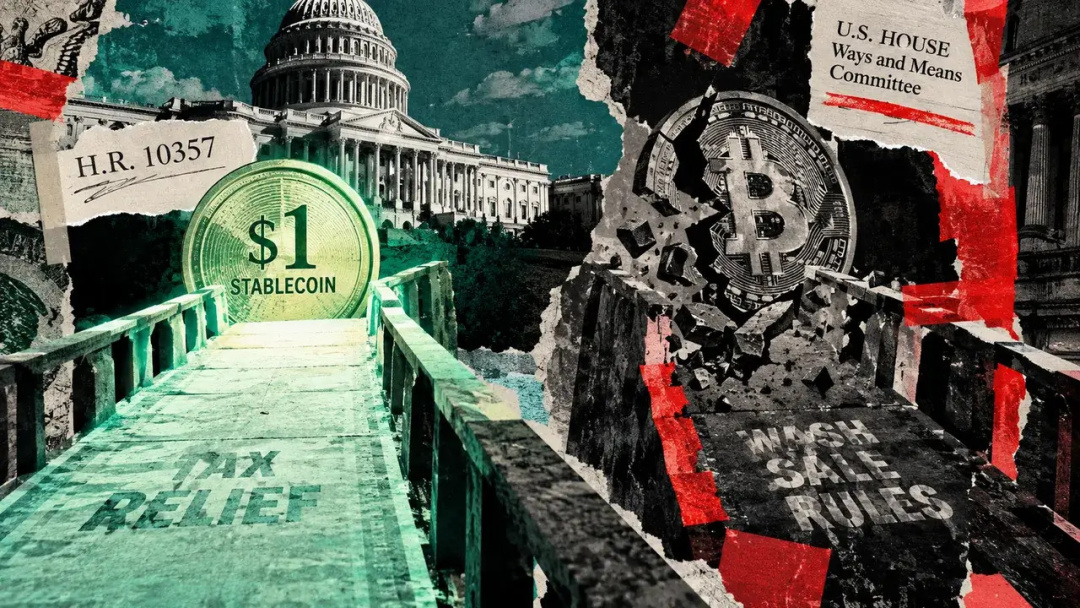
The House Ways and Means Committee is preparing to review H.R. 10357, known as the Digital Asset Tax Certainty Act, on September 16. This proposed legislation aims to reform the taxation of digital assets, potentially raising an estimated $500 million for the federal government from fiscal years 2027 to 2036. The Joint Committee on Taxation (JCT) has assessed that the bill will increase federal receipts while also easing the tax burden on stablecoin payments and minor transaction fees.
The legislation comes after extensive discussions on how cryptocurrencies should be treated in comparison to traditional financial assets. It includes new rules that address various aspects of crypto transactions, including stablecoins, transaction fees, trading losses, and digital asset lending. The central premise of the bill is to reduce the tax friction that currently complicates routine crypto activities, while simultaneously implementing securities-style regulations that could generate significant additional revenue.
Common Sense Shop
The United States of Common Sense
Amazon shopping links. Sponsor Complete!
Andrew Gordon, a tax lawyer specializing in cryptocurrency, remarked on the importance of clear tax rules for crypto investors, stating, "This is a massive step forward for crypto investors who simply want rules on tax. We all pay taxes, the rules need to be clear."
One of the key provisions of the bill involves the treatment of qualifying US dollar stablecoins. To avoid unnecessary tax calculations for minor fluctuations around their $1 peg, the legislation proposes that the redemption value will generally determine the basis for transactions occurring within specified limits. However, traders and certain high-volume users will not benefit from this provision.
Additionally, the bill proposes to disregard gains or losses for digital assets used to pay transaction fees of up to $10, which includes costs like blockchain gas fees. This provision, however, is projected to reduce federal receipts by approximately $2.365 billion through 2036.
In a significant shift, the legislation also seeks to apply wash sale rules to digital assets, which would eliminate a tax advantage that crypto investors have enjoyed over stock traders. This means that if an investor sells Bitcoin at a loss and buys it back immediately, they would no longer be able to claim that loss for tax purposes. The JCT estimates that this change could generate an additional $1.707 billion in federal revenue.
Expanding Tax Provisions for Digital Assets
Moreover, the bill aims to expand access to mark-to-market accounting for digital asset dealers, which is expected to raise $2.332 billion through 2036. These provisions are designed to help offset the tax relief offered elsewhere in the legislation.
Beyond trading, the proposed law extends tax treatment available for securities lending to qualifying digital asset loans, clarifying that temporarily transferring crypto under a lending agreement will not be treated as a taxable sale, provided certain conditions are met.
However, the legislation does not extend similar benefits to individual miners and stakers, as it classifies validation income as ordinary income and maintains the existing tax framework for staking rewards. This means that miners and stakers will still face immediate tax obligations upon gaining control of their rewards.
The Common Sense Test
For taxpayers with past reporting issues, the bill proposes a Digital Asset Voluntary Disclosure Program, allowing eligible individuals to rectify previous filings and potentially receive relief from penalties. As the committee prepares to mark up the bill, it will be the first test of whether the proposed compromises will withstand scrutiny and amendments during the legislative process.
The upcoming markup will be crucial in determining the final shape of H.R. 10357, with potential changes to the wash-sale, fee, and stablecoin provisions that could impact the projected $500 million in net revenue gains. Lawmakers will need to balance the desire for tax relief with the necessity of maintaining revenue for the federal government.