Supreme Court Rules on Michigan Family's Property Tax Foreclosure Case
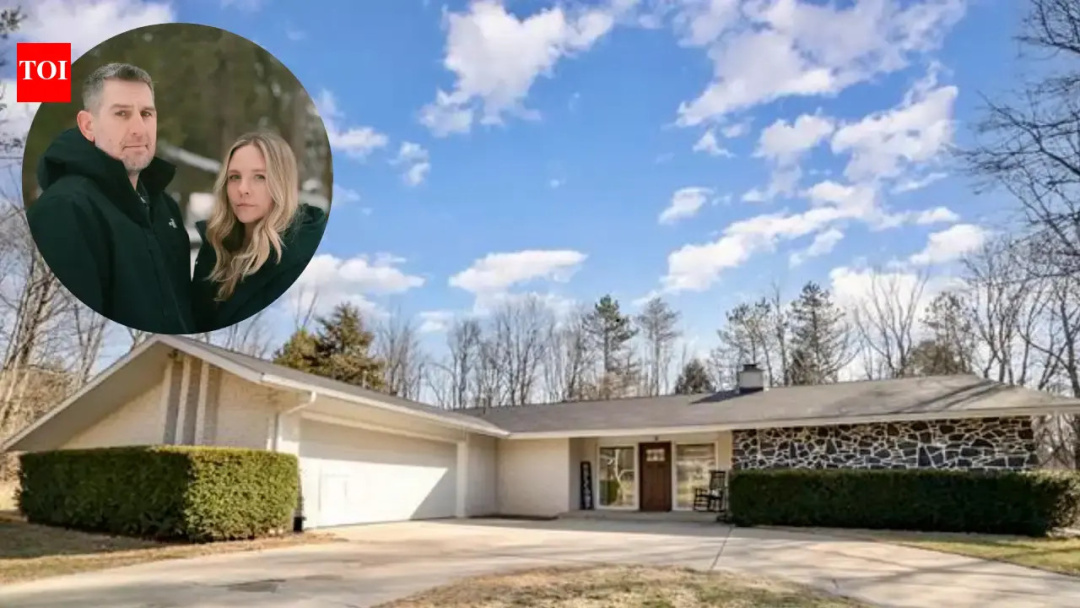
In a landmark decision, the United States Supreme Court ruled that a Michigan family, whose home was sold at a public auction over a $2,241 tax debt, is entitled to receive only the surplus cash from the sale, not the full market value of their home. This ruling, made in the case of Pung v. Isabella County, establishes a nationwide standard for how compensation is calculated after a tax sale. Justice Samuel Alito, writing for the majority, stated that the Fifth Amendment's requirement for "just compensation" is based on the actual auction price, not an estimated market value.
The legal battle began in Union Township, Isabella County, Michigan, where Scott Pung purchased a three-bedroom ranch-style home in 1991 for $125,000. After his death in 2004, his wife, Donnamarie, continued to live there until her death in 2008, after which their son Marc and his family took residence. The home remained under Scott Pung's estate, with Donnamarie and Marc as beneficiaries. In 2010, the local tax assessor removed the primary residence exemption, claiming the family failed to file an updated affidavit. Consequently, the property was taxed as a second home for several years, leading to a tax balance of $2,241.93.
Common Sense Shop
The United States of Common Sense
Amazon shopping links. Sponsor Complete!
Following the outstanding tax bill, Isabella County initiated foreclosure proceedings. A trial court initially blocked the foreclosure, but the Michigan Court of Appeals later allowed it to proceed. The county auctioned the property, which was assessed at $194,400, for only $76,008. An investor subsequently resold the home for $195,000 less than 18 months later. Despite the significant difference between the auction price and the assessed value, the county retained all proceeds from the sale.
Michael Pung, representing the estate of Timothy Scott Pung, filed a lawsuit against Isabella County, arguing that retaining the full value violated the Takings Clause of the Fifth Amendment. The federal District Court ruled that the county must return the surplus from the tax sale but denied Pung's claim for full market value compensation. The Sixth Circuit upheld this decision, determining that the former owner is entitled only to the amount exceeding the tax debt.
Supreme Court Clarifies Tax Sale Compensation
The Supreme Court's ruling on June 23, 2026, clarified that the auction price is the constitutional baseline for compensation after a tax sale, provided the sale is conducted fairly. Justice Alito noted that requiring payment based on hypothetical market values could impose excessive financial burdens on local governments, potentially making tax sales impractical. The Court emphasized the historical context of tax sales in both English and American law, asserting that governments have long utilized property sales to recover unpaid taxes while ensuring any surplus is returned to former owners.
The Common Sense Test
In a concurring opinion, Justice Sonia Sotomayor, along with Justices Neil Gorsuch and Ketanji Brown Jackson, agreed with the judgment but highlighted that the ruling does not set definitive standards for what constitutes a fair tax auction. The Supreme Court's decision vacated the Sixth Circuit's ruling, allowing for further proceedings to determine if the county's foreclosure and sale processes were fair. The family will receive the $73,766.07 surplus from the auction, rather than compensation based on the home's assessed value of $194,400.
This ruling underscores the importance of ensuring fairness in tax sales and the constitutional protections afforded to property owners. As local governments navigate the complexities of tax collection, this decision will likely influence how future tax sales are conducted and how compensation is determined.